BangladeshistBangladeshistBangladeshist
HomeBusinessEntertainmentGeneralOpinion
About UsContact UsPrivacy Policy
Terms of ConditionsFAQ
FacebookInstagramYouTubeTwitterTikTok
BangladeshistBangladeshist

© 2026 Bangladeshist. All rights reserved.

  1. Home
  2. Business
  3. How Remittances Support Bangladesh’s Economy
Business

How Remittances Support Bangladesh’s Economy

Remittances help millions of Bangladeshi families pay for food, education, healthcare and housing. Discover how money sent home by overseas workers supports local businesses, strengthens foreign-exchange inflows and contributes to Bangladesh's economic development.

PlabonnSunday, November 1, 202622 min read
How Remittances Support Bangladesh’s Economy

Every month, Bangladeshi workers living abroad send money to parents, spouses, children and other family members at home. That money pays for groceries, school fees, medical treatment, housing and everyday necessities. But its impact extends well beyond individual households: remittances also bring foreign currency into Bangladesh, support domestic businesses and help the country pay for imports.

The scale is substantial. Bangladesh Bank's annual data show that the country received approximately $35.59 billion in workers' remittances during the 2025–26 fiscal year, up from about $30.33 billion in 2024–25. That represents an increase of roughly 17.3% in one year. These are fiscal-year figures, not calendar-year totals.

The numbers help explain why overseas employment is such an important part of Bangladesh's economic story. Yet the full value of remittances cannot be measured in dollars alone. Their effects depend on how families use the money, how efficiently it reaches them, whether businesses can respond to additional demand and whether the country can turn the income into lasting economic gains.

What Are Remittances, and Where Does the Money Go?

Remittances are money transfers that migrants send to people in their home countries. In Bangladesh, they commonly come from workers employed in countries across the Gulf, Southeast Asia, Europe and North America.

A worker might send money every month to cover a family's food and utility bills, pay a child's tuition or help parents obtain medical care. Another might send a larger amount to renovate a home, purchase agricultural equipment or establish a small business.

These transfers can be particularly important when the receiving household has limited opportunities to earn a stable income locally. Remittances give families an additional source of money that may help them cope with unemployment, illness, seasonal income fluctuations or unexpected expenses.

The money does not all go into savings or investment. Much of it supports ordinary consumption, and that is not necessarily a weakness. Food, housing, education and healthcare are fundamental to household welfare. When a family can afford better nutrition, keep children in school or seek medical treatment earlier, the benefits may extend well beyond the immediate transaction.
Read More

All Stories in Read More →
Bangladesh Garment Factories Reopen as Tk 30,000 Wage Protests Continue
Business

Bangladesh Garment Factories Reopen as Tk 30,000 Wage Protests Continue

Bangladesh's garment factories are reopening after widespread disruption, but workers continue demanding a Tk 30,000 monthly minimum wage. A new wage board has begun the review process, leaving the dispute unresolved.

7 min readNov 2
Bangladesh Looks to Thailand to Boost Exports as New Shipping Route Cuts Transit Time
Business

Bangladesh Looks to Thailand to Boost Exports as New Shipping Route Cuts Transit Time

Research on Bangladeshi households has found associations between remittance receipt and higher spending on consumption, education and healthcare. A 2024 study examining migrant families in Tangail and Cumilla reported positive effects on several household expenditure categories. Such findings provide evidence of potential benefits, although results from particular samples should not automatically be treated as estimates for every household in Bangladesh.

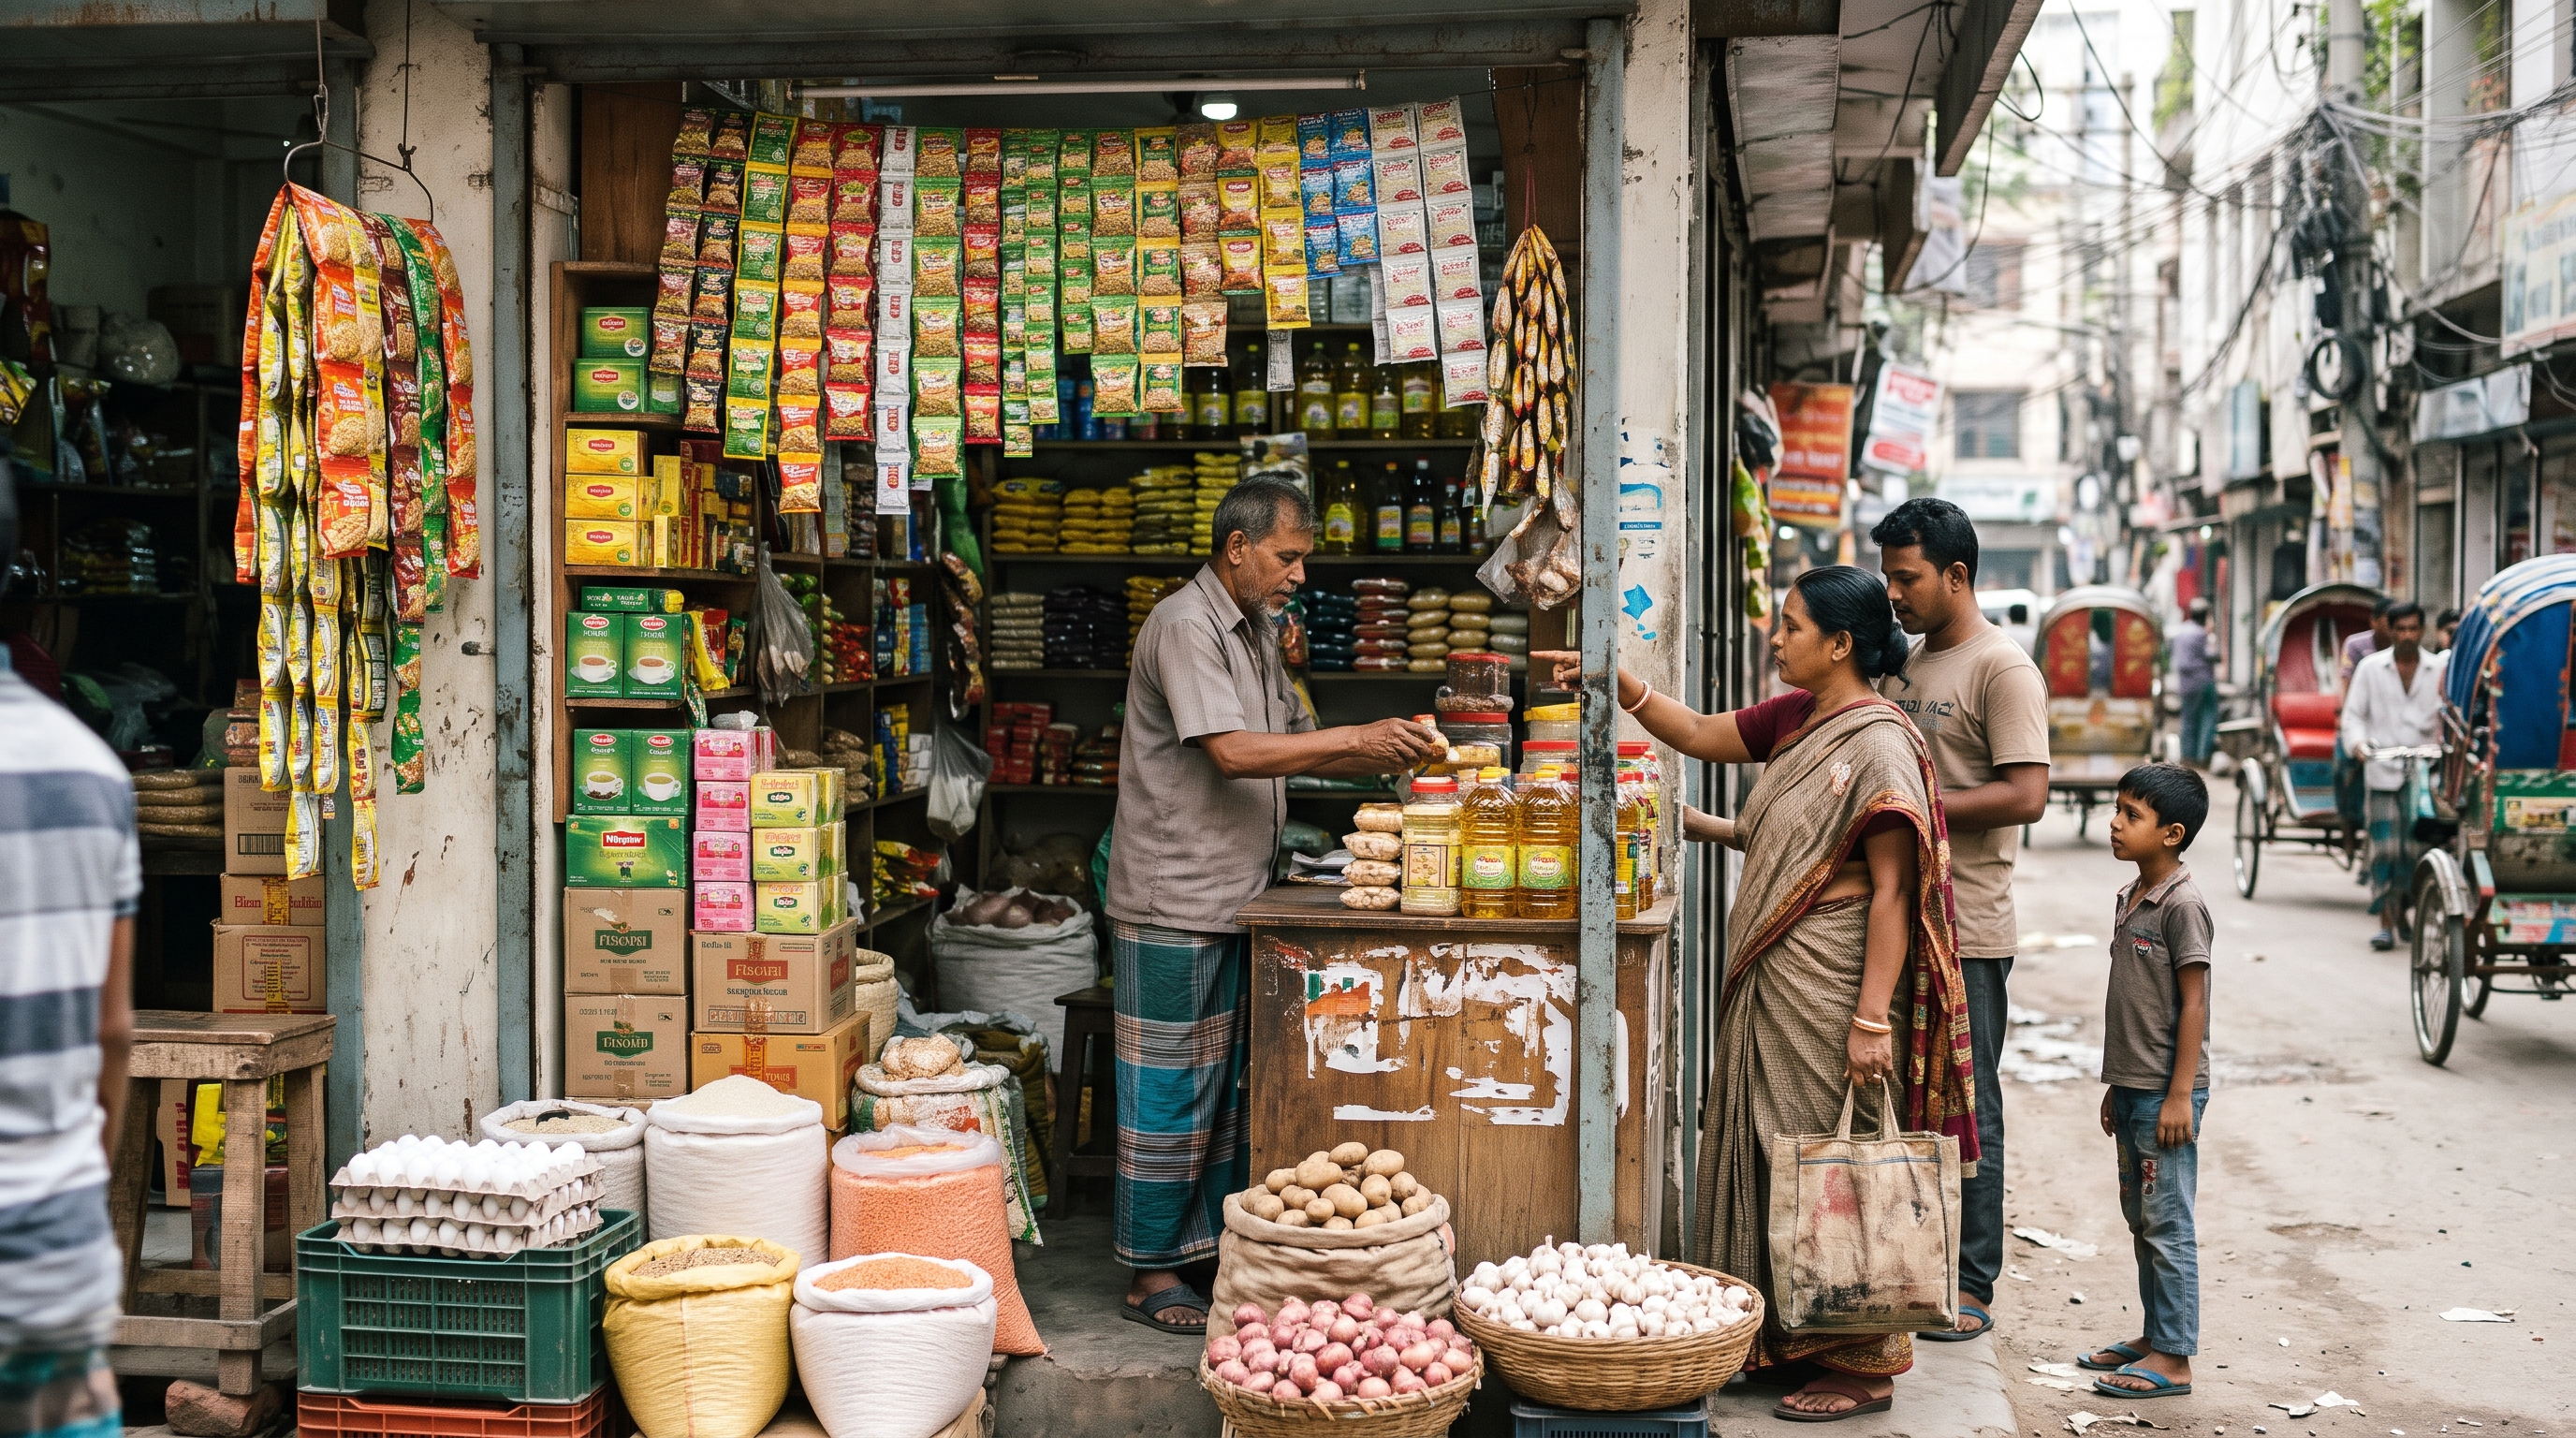
Spending supported by remittances can generate income for local shops and service providers.

How Remittances Strengthen the National Economy

One of the most important contributions of remittances is the foreign currency they bring into Bangladesh. The country needs foreign exchange to pay for imported fuel, machinery, industrial raw materials, food and other goods. Export earnings and foreign investment also supply foreign currency, but remittances provide another major source.

When remittances enter through formal financial channels, banks and the wider financial system can record and process those inflows. The foreign currency helps support the country's external payments position, although the overall outcome also depends on imports, exports, debt payments, capital flows and other transactions.

Bangladesh Bank's Financial Stability Report 2025 described remittances as an important source of support for the external sector, noting that inflows helped offset the trade deficit. It reported remittance receipts of approximately $30.33 billion in fiscal year 2024–25 and continued strong inflows in the first half of fiscal year 2025–26.

Remittances can also ease pressure on foreign-exchange availability. When more foreign currency enters the formal system, it can improve the capacity of banks and the economy to meet legitimate foreign-currency needs. That does not guarantee a stronger taka or automatically increase foreign-exchange reserves by the same amount: imports, repayments, central-bank operations and other flows determine the final result.

The money also supports local demand. A family receiving remittances may purchase more goods from a neighbourhood grocery shop, pay a builder to repair a house, hire a tutor or buy supplies from a local business. Those payments become income for other people, who may then spend some of it elsewhere.

This circulation can support economic activity in villages, towns and cities. The effect is especially meaningful where remittance income reaches communities with relatively few well-paid local employment opportunities.

However, higher household spending does not translate entirely into domestic production. Some of the additional demand goes toward imported goods, while some may be absorbed by rising prices or spent on assets that create limited new productive capacity. The wider economic benefit depends on the ability of local businesses and producers to respond.

How Families Benefit: Education, Healthcare and Security

For many recipients, the most direct benefit is greater financial security. A regular transfer can help a family plan its monthly expenses instead of relying entirely on uncertain earnings from farming, casual work or small businesses.

Education is one area where remittances can make a lasting difference. Families may be better able to pay school fees, purchase books, cover transport costs or support a child through further study. These investments can improve future employment opportunities, although better outcomes are not automatic and also depend on education quality and access to work.

Healthcare is another important use. Remittance income can help families pay for consultations, medicines, diagnostic tests and treatment that might otherwise be delayed. A 2026 study using Bangladesh's Household Income and Expenditure Survey 2022 data estimated that remittance-receiving households spent approximately Tk 2,000–2,300 more per year on healthcare than comparable non-recipient households under the study's matching approach. This is a research finding for the data and method used, not a universal spending difference for every family.

Remittances may also help families improve housing, acquire land, build savings or recover from financial shocks. These gains can reduce vulnerability and make it easier for households to make longer-term plans.

But migration can impose costs on the family, too. Workers may pay recruitment fees, borrow money to travel, spend long periods separated from relatives or face uncertain employment conditions abroad. If migration costs are high, it can take a long time before the family receives a net financial benefit. The money sent home must therefore be considered alongside the costs and risks of obtaining overseas employment.

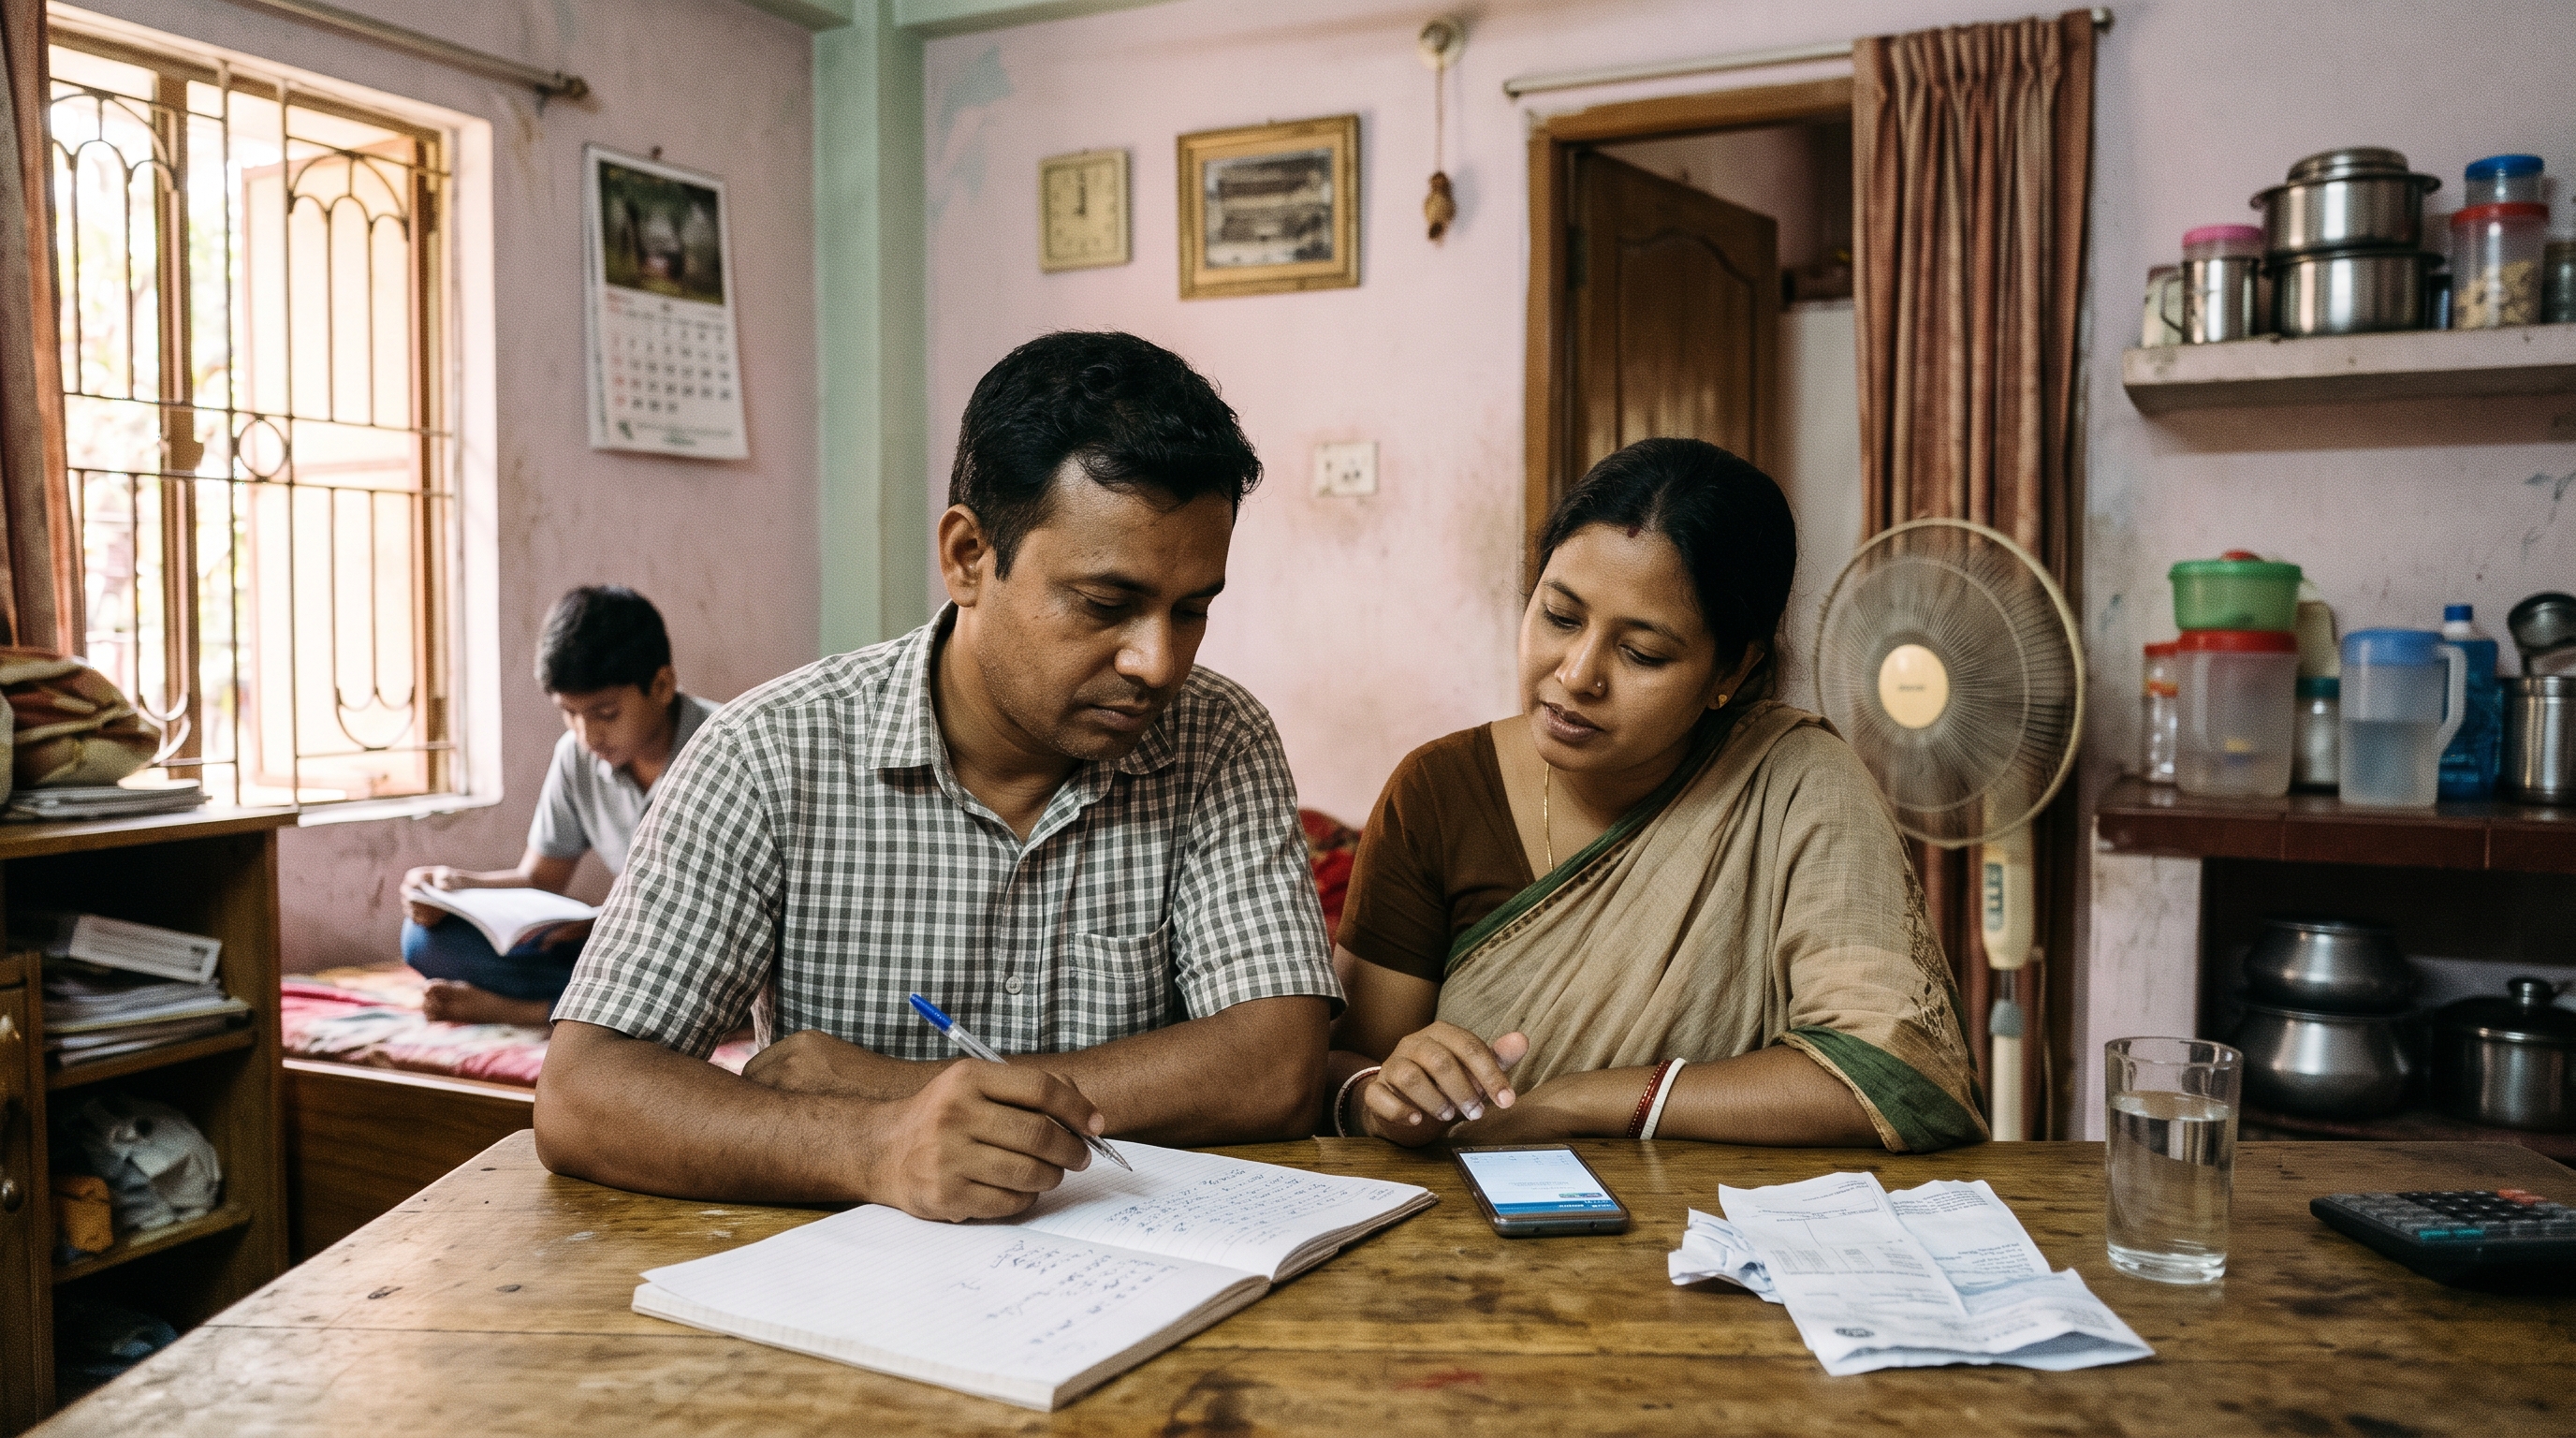
Remittance income can help families cover everyday expenses, education and healthcare.

Why Small Businesses and Local Markets Matter

Remittances can create opportunities for local businesses by increasing the purchasing power of customers. A household that previously struggled to meet essential expenses may begin buying additional goods, paying for repairs or using services that were previously unaffordable.

Some recipients use part of their money to start a shop, purchase livestock, invest in agricultural activities or expand an existing business. These investments can generate income at home and potentially create employment for other people.

The transition from remittance income to productive investment, however, is not automatic. Starting a business requires market knowledge, skills, reliable electricity and transport, access to customers, and sometimes credit or formal registration. A household may reasonably prefer to spend its money on essential needs or retain savings rather than risk it in a business.

Research on remittance use in Cumilla has identified constraints such as limited investment knowledge and a shortage of attractive opportunities. Although findings from one district cannot represent every part of the country, they illustrate why access to training, sound financial services and viable local enterprises matters.

Policies that help small businesses operate more efficiently can therefore increase the chance that some remittance-supported spending leads to lasting economic activity. Financial education, transparent lending, business advisory services and better local infrastructure can all play a role.

The Importance of Formal Remittance Channels

How money reaches Bangladesh matters as much as how much is sent.

Formal channels, including banks and licensed money-transfer providers, create a recorded transaction and can provide legal safeguards and traceability. They also help official statistics capture inflows and give recipients access to established financial services.

Informal transfers may be attractive when they appear faster, cheaper or easier to use. But they can expose senders and recipients to fraud, disputes, weaker legal protections and difficulties proving that a payment occurred. They also reduce the visibility of flows in official financial data.

The cost of sending money is an important factor. Fees, exchange-rate margins, access to transfer providers and the time required to collect funds all affect how much a family ultimately receives. Improving competition, expanding convenient digital services and making exchange rates and fees more transparent can help workers deliver more value to their families.

Bangladesh's experience also shows why incentives and confidence in formal channels matter. Bangladesh Bank's reporting has linked stronger official inflows in recent years to policy measures encouraging formal transfers and changes in the gap between official and informal exchange rates. These factors can influence the recorded total without necessarily indicating an equal change in the amount workers earn or the amount families need.

Why Remittances Cannot Replace Broader Economic Development

Large remittance inflows provide meaningful support, but they cannot solve every economic problem.

Remittances depend on employment and income earned abroad. A slowdown in destination countries, changes in immigration rules, weaker demand for migrant labour or conflict can affect workers' ability to send money home. Families that depend heavily on one migrant may face particular risks if that person loses a job or becomes unable to work.

Migration can also have domestic trade-offs. When skilled or working-age people leave, some communities and industries may lose workers. The overall result depends on who migrates, the jobs they take abroad, the opportunities available at home and whether returning migrants bring back savings, skills and business experience.

There is also a difference between foreign currency entering the country and domestic productive capacity expanding. Remittances can support imports and consumption, but sustainable growth requires a strong base of productive businesses, reliable infrastructure, education, healthcare, competitive exports and opportunities for decent work at home.

Bangladesh therefore benefits most when remittances complement, rather than substitute for, economic development. A healthy remittance system should protect migrant workers, reduce unnecessary transfer costs, support household financial security and make it easier for interested recipients to invest safely.

Turning Remittances Into Long-Term Gains

The next stage of Bangladesh's remittance story is not simply about increasing the headline figure. It is also about improving the conditions under which workers migrate, families receive money and the wider economy uses the resulting income.

Safer recruitment, clear employment contracts, access to reliable financial services and protection against exploitation can reduce the risks faced by migrant workers. Affordable formal transfers can help ensure that more of their earnings reach the intended recipients.

At home, better education, healthcare, transport, electricity and access to finance can help families and businesses convert income into improved living standards and productive activity. Recipients should have the freedom to decide what their families need; investment should be encouraged through opportunity and support, not by treating essential household spending as wasteful.

Remittances are ultimately the result of people's work, often performed far from home and under difficult conditions. Their economic contribution is visible in foreign-exchange flows and household spending, but their value is also reflected in school attendance, medical care, housing security and the choices families are able to make.

For Bangladesh, the challenge is to protect this vital connection between workers abroad and households at home while building an economy in which people can also find secure, productive and fairly paid work without having to leave the country.

Tags:#Bangladesh Economy#Remittances#overseas employment#migrant workers#Household Income#Economic Development#Small Business#Financial Inclusion#Foreign Exchange
share:

Comments

0

Join the discussion

You must be logged in to leave a comment.

Loading comments…

Most Read

1

Benin Thrash India 27–0 at U18 School Football World Cup

Oct 22
2

HSC Results 2026: When and How to Check Results in Bangladesh

Oct 29
3

Toyota Solid-State EV Battery Enters Early Mass Production

Oct 10
4

NASA Delays Artemis Moon Landing to 2028 Over Starship Issues

Oct 8
5

E-Commerce Business Guide: How to Properly Set Up an Online Storefront

Jun 16

Popular Tags

#Bangladesh Economy#Barcelona#Artificial Intelligence#Inflation#Energy Security#Global Economy#UEFA Champions League#Bayern Munich#Public Health#Bangladesh Bank#Real Madrid#PSG

Bangladesh wants Thailand to buy more pharmaceuticals and jute products as a new shipping connection promises faster cargo transport and both countries explore closer trade ties.

8 min readOct 31
Alphabet’s $9 Billion Cash Burn Puts AI Spending Under Investor Scrutiny
Technology

Alphabet’s $9 Billion Cash Burn Puts AI Spending Under Investor Scrutiny

Alphabet’s shares plunged 12.6% after its latest earnings highlighted the financial strain of AI investment, even as Google Cloud revenue more than doubled.

7 min readOct 30
Anthropic Files for IPO as AI Boom Meets Questions Over Growth, Costs and Risk
Technology

Anthropic Files for IPO as AI Boom Meets Questions Over Growth, Costs and Risk

Anthropic has filed to go public under the ticker ANT, bringing fresh attention to the AI company's rapid revenue growth, financial disclosures and technology risks.

8 min readOct 28
More stories in Business